Staci Roberts helped a first-time buyer in Hidden Valley Lake, California, reduce her estimated cash to close from $21,000 to $11,000 by negotiating a $10,000 seller credit. The buyer, a teacher purchasing on her own, had enough income to qualify for financing but limited savings for the down payment and closing expenses, so Roberts built the transaction around the cost standing between her client and homeownership.
The credit reduced the buyer’s expected out-of-pocket requirement by nearly 48%. Roberts produced that shift by completing the financial preparation first, finding a property below the buyer’s approved amount and submitting an offer that gave the seller value in exchange for help with closing costs.
Limited Savings Defined the Real Affordability Problem
The buyer did not begin the process believing she had a clear path to ownership. She worried that the amount of money required at closing would keep her from buying, even though she could qualify for a mortgage and manage the resulting monthly payment.
Roberts recognized the difference between being unable to afford homeownership and being unable to cover a large upfront expense. The buyer’s estimated $21,000 cash-to-close requirement created the immediate barrier, not the long-term cost of the mortgage.
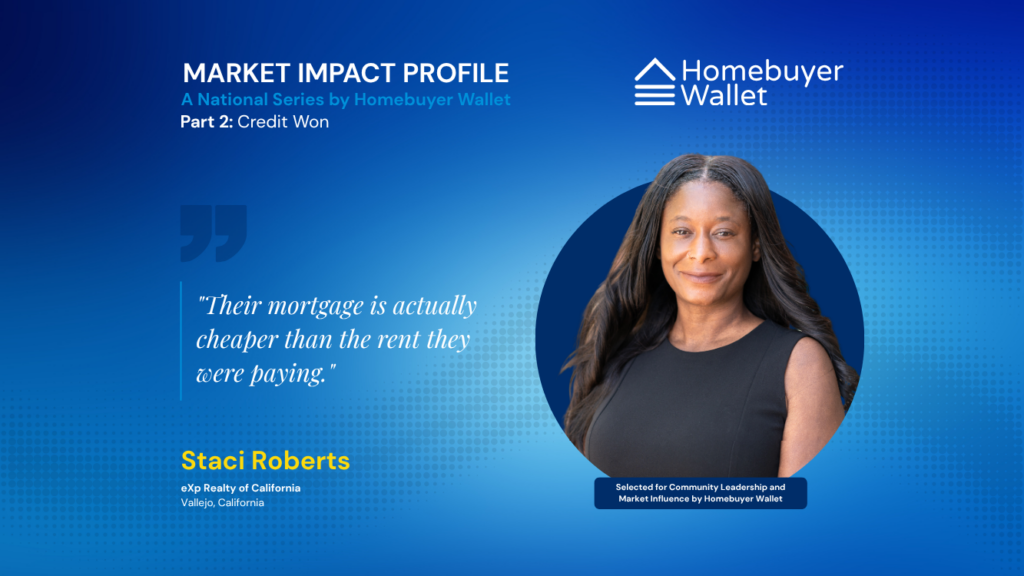
“They did not think they would be able to afford the home with limited cash,” Roberts said. “Their mortgage is actually cheaper than the rent they were paying.”
That contrast shaped the entire transaction. Roberts did not respond by pushing the buyer toward the top of her budget or treating a lower sales price as the only available solution. She focused on reducing the amount the buyer would need to produce at closing while protecting the financing and the buyer’s preferred monthly payment.
Cash-to-close strategy means structuring a purchase to reduce the buyer’s immediate out-of-pocket burden. For Roberts, that required treating the preapproval, home search, offer price, seller credit and closing schedule as parts of one coordinated plan.
The approach fit the buyer’s position in Northern California’s North Bay market, where Roberts typically works with purchasers in the $330,000 to $500,000 range. A down payment of 3% to 5% can still leave a buyer responsible for thousands of dollars in closing expenses, which Roberts estimates can reach approximately $12,000 in the transactions she handles.
Preapproval Turned a Budget Into Leverage
Roberts begins with the preapproval process because she does not want buyers searching without a defined financial range. She uses the lender’s analysis to identify the maximum purchase amount, the estimated monthly payment and the cash demands the buyer must prepare to meet.
“The preapproval process is where I start all my buyers,” Roberts said. “I do not like looking at homes until we can tailor down what your budget is.”
That sequence gave Roberts information she later used during the Hidden Valley Lake transaction. She knew how much the buyer could finance, but she also knew the buyer could not comfortably absorb the original $21,000 cash requirement.
The completed preapproval also made it possible to present the buyer as prepared rather than financially uncertain. Roberts said that distinction matters in Vallejo, California, and other parts of the North Bay, where well-positioned homes can still attract multiple offers even when some properties remain available for more than 60 days.
“Having preapproval paperwork finished and in hand gives leverage with sellers,” Roberts said.
Roberts typically targets a closing period of 15 to 21 days after offer acceptance. That speed depends on a buyer who has already gathered pay records, bank statements and other documents that the lender may require, so Roberts treats incomplete paperwork as a strategic weakness rather than an administrative inconvenience.
In this case, the buyer’s limited cash did not make the offer inherently weak. Roberts could show that the buyer had completed the financing work, understood her budget and could support an efficient closing once the parties agreed on terms.
An Overlooked Property Created Financial Room
The home that ultimately worked was not one the buyer initially wanted to see. Roberts recommended it after looking beyond the buyer’s original list and matching the property against the priorities she had repeated throughout their work together.
The buyer wanted space for a garden, owned solar and a purchase price she could manage without stretching her finances. The single-family home in Hidden Valley Lake included solar and an additional parcel of land, giving the buyer room to garden while delivering more property than she expected to find within her budget.
“This home wasn’t on her list, but when I saw the owned solar, an extra parcel of land for her to garden and a price below what she approved for, I suggested we look at it even though she had no initial interest in this property,” Roberts said.
The price below the buyer’s approved amount mattered as much as the physical features. Roberts did not treat the preapproval ceiling as a spending target, and she did not assume that using every available dollar would create the strongest outcome.
Instead, she found a home that preserved financial breathing room. That gave her a better foundation for addressing the buyer’s closing expenses without forcing the buyer to sacrifice the solar, outdoor space or affordability goals that had guided the search.
Roberts’ recommendation also reflected the patience behind her work with first-time buyers. She met the buyer at an open house in Vallejo in November, but they did not complete a purchase until May. During those months, Roberts listened for the priorities that remained consistent and used them to identify a property the buyer might have dismissed on her own.
“I was patient, and I listened to the items that they kept repeating were important,” Roberts said.
Credible Offer Terms Made the Seller Credit Work
Roberts did not attempt to solve the buyer’s cash shortage with a low offer. She submitted a full-price offer and paired it with clean terms and a quick closing commitment, giving the seller greater certainty while requesting a $10,000 credit toward the buyer’s costs.
“Pricing is important,” Roberts said. “You do not want to provide a lowball offer. If hoping for price flexibility, it is good to be realistic.”
The offer focused the negotiation on the buyer’s actual constraint. A lower purchase price might have reduced the loan balance, but it would not necessarily have lowered the amount the buyer needed to bring to closing by $10,000.
The seller credit addressed that problem directly. It reduced the estimated cash to close from $21,000 to $11,000, allowing the buyer to complete the purchase with nearly half the upfront amount she initially expected to need.
Roberts made the request more credible by avoiding an offer structure that asked the seller to concede on every major point. She offered the listed price, presented a prepared buyer and committed to a streamlined closing, then concentrated the financial negotiation on the credit that would determine whether her client could move forward.
That balance distinguished the strategy from a simple request for assistance. Roberts gave the seller a reason to consider the credit because the rest of the offer reduced uncertainty and supported an efficient transfer.
The appraisal later came in above the purchase price. That result gave the buyer additional reassurance that the full-price offer and seller credit had not required her to purchase a home worth less than the amount stated in the contract.
Tight Coordination Protected the Negotiated Terms
The accepted offer did not eliminate the risk of delay. A holiday interrupted the transaction, the lender requested additional documentation from the buyer, and both the inspection and appraisal processes fell behind the intended schedule.
Those complications placed pressure on the quick-closing terms that had helped Roberts secure the seller’s agreement. She had to keep the buyer, lender, title professionals and other parties aligned while making sure the outstanding work did not undermine the negotiated credit.
“I go above and beyond and make sure that everyone from the lender to title is kept on the same page,” Roberts said. “It is important that communication is constantly flowing.”
Roberts’ role as director of operations for a school serving students with autism and other intellectual disabilities has shaped that coordination style. Her work with families and outside vendors taught her to listen closely, communicate across several parties and negotiate without losing sight of the person affected by each decision.
The transaction closed in fewer than 30 days despite the holiday, underwriting requests and delayed inspections and appraisal. Roberts did not achieve her usual 15- to 21-day target, but she preserved the agreement and kept the buyer moving toward a closing that had once seemed financially impossible.
The final clear-to-close decision became the turning point for Roberts and her client. The buyer had spent months wondering whether limited savings would prevent her from purchasing, and the lender’s approval confirmed that the credit, financing and closing work had held together.
“My client was beyond overjoyed,” Roberts said.
Reduced Upfront Costs Changed the Buyer’s Timeline
The $10,000 seller credit did more than lower a number on the closing disclosure. It allowed the buyer to purchase a single-family home with owned solar and additional land while bringing approximately $11,000 to closing instead of the original $21,000 estimate.
The buyer also moved from renting into a mortgage payment that Roberts said was lower than her previous rent. The result gave her the garden space she wanted, a home she could afford on her own and a property that appraised above the agreed purchase price.
Roberts created that outcome by staying focused on the buyer’s specific financial gap. She completed the preapproval before the search intensified, kept the purchase price below the buyer’s approved amount, identified an overlooked property and used a full-price offer with clean terms to negotiate the credit.
Her approach did not depend on presenting the buyer as someone who needed to be rescued from an unaffordable purchase. It presented her as a qualified buyer who needed the transaction arranged around the cash she actually had available.
That distinction is central to Roberts’ work with first-time buyers and women purchasing on their own in Vallejo and across California’s North Bay. She does not rush clients into homes simply because they qualify, and she does not assume limited savings should end the search before a buyer understands every workable option.
“Patience and flexibility will get you into the home of your dreams,” Roberts said.
For this buyer, patience uncovered the right property and flexibility shaped the right offer. Roberts then used a $10,000 negotiation to turn an estimated $21,000 barrier into an $11,000 path to ownership.
Want to connect with Staci? You can visit her website, follow her on Instagram, Facebook, or TikTok. You can also email her directly for more information.