Aaron Peters sees the same pattern across the rural Missouri communities he serves: buyers can still find affordability, but they cannot treat affordability like permission to move slowly. In his market, a typical buyer may purchase between $160,000 and $300,000, often for a single-family home between 1,200 and 2,000 square feet, but the move-in-ready homes priced between $140,000 and $190,000 can disappear quickly when buyers arrive without a plan.
Affordability Still Exists, But Speed Changes the Rules
In many higher-cost markets, buyers are trained to assume that a lower price means something must be wrong. Peters hears that reaction from out-of-state buyers who look at rural Missouri listings and struggle to reconcile the price with the condition of the home, the size of the property or the monthly payment that may come with it.
“In the grand scheme of things, you can purchase real estate affordably in my area compared to a lot of other out-of-state areas,” Peters said. “I have had a lot of out-of-state buyers call me about listings to ask, ‘What is wrong with the home and why is it listed so low?’ when in my market, it is priced accordingly.”
That pricing reality creates the opportunity, but it also creates the trap. Buyers who assume a rural Missouri listing will sit because it is affordable can lose ground to someone who already has financing in place, understands the local value and can write a serious offer without hesitation.
The typical numbers show why the market attracts attention. Peters said buyers often enter with estimated down payments ranging from $0 to $7,500, estimated closing costs of about $5,000 to $6,000 between title and lender costs, and monthly payments that often fall between $1,200 and $1,800. In a title and escrow state where closings commonly take 25 to 30 days, preparation matters before the contract ever starts.
The Strongest Buyers Are Prepared Before the Search Turns Emotional
In Peters’ market, the most important buyer move often happens before the showing. Buyers need a pre-approval, a clear budget and a plan that matches their actual situation because the homes that solve affordability problems do not always wait for buyers to get organized.
“Homes in the $140,000-$190,000 price range that are move-in-ready go quickly,” Peters said. “You MUST be ready to roll with a pre-approval in hand and personalized plan for your own situation if you find a home in this range that meets your needs.”
That is the central strategy behind Peters’ market guidance. He does not treat pre-approval as a paperwork step at the end of the search. He treats it as the starting point that lets a buyer recognize the right home, understand the true cost and act before the opportunity passes.
Buyer readiness means having the financing, local context and offer strategy in place before a desirable home creates pressure.
That approach matters because Peters’ buyers are often balancing affordability, location and proximity to work or family. He said his area does not have many large towns, so buyers often choose based on the closest rural setting that keeps them near the people or workplace that anchor their daily life. The search is personal, but the execution has to be disciplined.
Offer Strategy Can Protect Buyers From Costly Assumptions
Peters sees one mistake more than almost any other: buyers try to low-ball a well-priced home because they believe negotiation is something they are supposed to do. In a low-inventory market, that assumption can weaken an offer before the seller ever considers the buyer’s story, financing or timeline.
“Trying to low-ball offer a well-priced home because that is what they feel you are ‘supposed to do,’” Peters said. “Guidance when working/talking through an offer is key here.”
That guidance is not about telling buyers to overpay. It is about helping them understand when a price already reflects the local market, the condition of the home and the competition likely to appear. In Peters’ market, a buyer who misreads a fair price as an invitation to test the seller may lose the home to someone who understood the listing correctly from the start.
The strategy depends on local judgment. A $180,000 move-in-ready home in one rural Missouri municipality may attract immediate attention, while another property at a similar price in a different town may require a different read. Peters’ value comes from helping buyers separate a real negotiation opportunity from a situation where hesitation simply gives another buyer the advantage.
Local Lender Alignment Replaces One-Size-Fits-All Program Advice
Peters does not force a single financing program into every buyer’s plan. When buyers ask about assistance or loan options, he points them toward local lenders who can match the available financing to the buyer’s actual income, credit profile, purchase price, location and timeline.
“Whenever it comes to programs, I trust our local lenders to be the expert in what program fits each client’s situation best,” Peters said.
No specific named assistance program was provided in the transcript, and Peters’ strategy is stronger because it avoids pretending that every buyer needs the same product. His role is to make sure the buyer gets aligned early with the right lender, understands the likely cash needed to close and enters the search with numbers that fit the real market.
That alignment matters when down payments may range from $0 to $7,500 and closing costs may add another $5,000 to $6,000. A buyer who only looks at the listing price may underestimate the cash needed to close, while a buyer who speaks with the right lender early can understand whether their path depends on loan structure, assistance eligibility, seller concessions or a different purchase price target.
Rural Expertise Lives Municipality by Municipality
Peters’ market is not one uniform rural area. He serves communities where each municipality has its own buyer demand, inventory pattern, price behavior and local appeal, and he believes buyers need an agent who can interpret those differences before they make decisions.
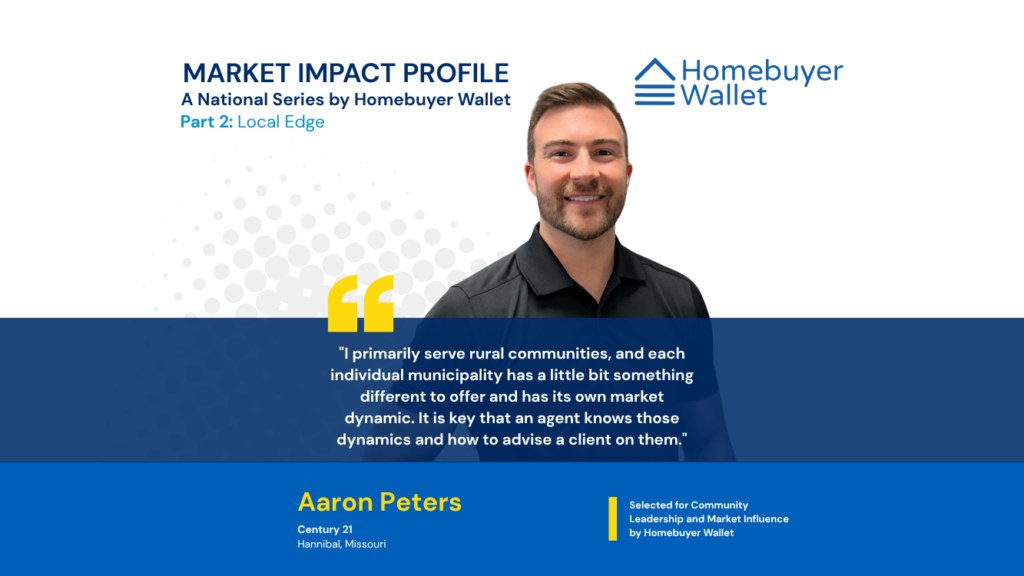
“I primarily serve rural communities, and each individual municipality has a little bit something different to offer and has its own market dynamic,” Peters said. “It is key that an agent knows those dynamics and how to advise a client on them.”
That local reading affects more than neighborhood preference. It shapes how quickly a buyer should act, how an offer should be positioned and how the buyer should compare value across nearby towns. A home that looks inexpensive to someone moving from another state may simply be priced correctly for that municipality, while a home that looks ordinary online may sit in a community where demand is stronger than the photos suggest.
Peters also sees financial differences that matter to buyers crossing into Missouri. He said several counties he serves have relatively lower tax rates, which buyers appreciate, especially those moving across the river from Illinois. For those buyers, the decision is not just about the purchase price; the local tax environment can influence how affordable the home feels month after month.
Overlooked Segments Are Creating the Next Openings
Peters sees opportunity in places that require closer local attention. He points to North County, St. Louis, Missouri, as an undervalued area where investors are rehabbing distressed houses and turning them into homes people can be proud of.
That matters because it shows how opportunity can emerge before broad market perception catches up. Buyers who only chase the obvious listings may miss areas where the housing stock, renovation activity and pricing still create a practical path into ownership.
He also sees intense demand in the condo market. Peters said the condo market in his area is “absolutely insane,” with available condos usually going under contract within one day. His read is simple: more condos are wanted and needed, and the speed of that segment proves how sharply demand can concentrate when buyers find a more accessible ownership option.
That is why Peters keeps returning to preparation. Rural Missouri may still offer affordability compared with many outside markets, but the best opportunities require buyers to know their numbers, understand the municipality, trust the financing process and write offers that match the speed of the market.
“It is low inventory, fast moving, and needs a plan set in place to feel confident about making the right move,” Peters said.
Want to connect with Aaron? You can follow him on Instagram, Facebook, or TikTok, or send him an email directly for more details.