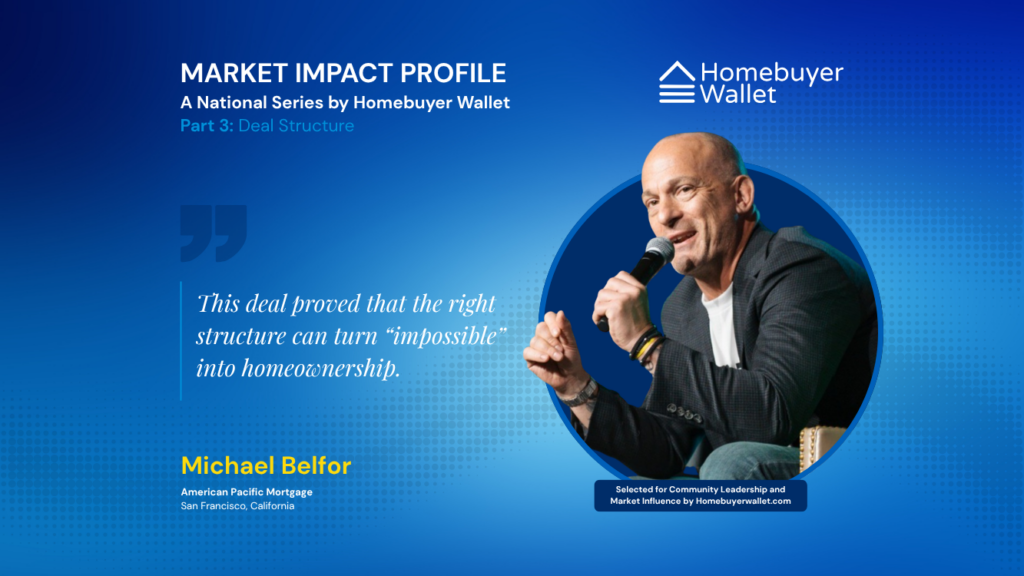
Michael Belfor structured a home purchase in Santa Rosa, California, with nearly 100% financing by combining a Section 8 homeownership voucher, an FHA-insured loan, and down payment assistance into a single transaction. The buyer, a first-time homeowner and single mother raising a disabled son, closed with little to no cash out of pocket on a mid-range townhome. “It was something she didn’t think was possible,” Belfor said, describing a deal that redefined what entry into this market can look like when financing is built instead of assumed.
Program stacking turns homeownership from a cash barrier into a coordination challenge, where the right combination of financing tools can eliminate upfront cost and make buying possible.
Layered Financing Replaces the Traditional Down Payment Model
Belfor did not approach this transaction with a fixed assumption about down payment requirements. He built the capital stack by aligning three separate sources of funding, each solving a different part of the financial equation.
The Section 8 Homeownership Voucher Program, administered through local housing authorities, reduced the buyer’s monthly housing burden by subsidizing a portion of the payment. The FHA loan, backed by the Federal Housing Administration, allowedallows for flexible credit standards and a low down payment structure. Down payment assistance programs, sourced at the local and state level, covered most or all ofall the upfront cash required to close.
Together, these programs replaced what would typically be tens of thousands of dollars in cash with layered support tied to income, eligibility, and property compliance. “Many buyers don’t realize what’s available,” Belfor said. “They assume the barrier is cash, but it’s usually knowledge.”
Voucher-Based Homeownership Expands the Definition of Buyer Readiness
The presence of a Section 8 homeownership voucher shifted how Belfor evaluated readiness. Instead of focusing only on savings, he analyzed how the voucher could function within a mortgage structure and whether the property would meet program standards.
The process began with a standard loan application, including income and asset review, but quickly extended into coordination with the buyer’s caseworker. The home itself had to qualify under voucher guidelines, and the loan terms needed to align with both FHA requirements and housing authority rules.
This dual qualification process required precision early. Belfor ensured that both borrower and property met program thresholds before advancing, avoiding the common failure point where financing approval and program approval fall out of sync late in the transaction.
Cross-Program Coordination Becomes the Real Barrier to Entry
The complexity of the deal did not come from the buyer’s profile. It came from managing the intersection of three independent systems that do not naturally align.
Belfor coordinated daily between the buyer, the lender, and the Section 8 caseworker to keep timelines and documentation consistent. Each party operated under different requirements, and delays in one channel could disrupt the entire structure.
“Daily communication with all parties helped navigate challenges and keep the deal together,” he said. That cadence allowed him to identify issues early, whether tied to documentation, property eligibility, or loan conditions, and resolve them before they escalated into delays or denials.
The execution depended less on any single approval and more on keeping all approvals moving at the same pace.
Daily Communication Keeps Complex Deals Intact
Belfor treated communication as an operational strategy rather than a soft skill. He maintained constant visibility across every moving part of the transaction, ensuring that no requirement went unaddressed or unnoticed.
That approach proved critical as conditions shifted throughout the process. When questions arose about program compliance or documentation, Belfor addressed them in real time rather than allowing them to accumulate.
“Communication and transparency are everything,” he said. “Staying ahead of issues keeps deals moving.” His role became less about reacting to problems and more about preventing them from forming in the first place.
Down Payment Assistance Remains the Most Overlooked Leverage Point
Despite the complexity of the structure, Belfor points topoints down payment assistance as the most underutilized piece of the equation. Many buyers who qualify never explore it, either because they are unaware of its existence or assume it is too restrictive.
In this transaction, down payment assistance closed the final gap, allowing the buyer to move forward without the savings typically required in a market like Santa Rosa, California. Without it, the deal would not have worked, even with the voucher and FHA financing in place.
“Down payment assistance programs are incredibly powerful and often overlooked,” Belfor said. That observation reflects a broader pattern he sees across the market, where access exists but remains disconnected from the buyers who need it most.
Stability, Not Just Ownership, Defines the Outcome
The result of the transaction extended beyond the mechanics of financing. The buyer transitioned from housing uncertainty into long-term stability, securing a home where she and her son could settle and invest in their future. That is life-changing.
Belfor continues to measure success by what happens after closing. He has watched the buyer begin improving the home and building a sense of permanence that renting could not provide.
“It’s more than a transaction, it’s impact,” he said. That outcome reinforces his approach to financing as a tool for access, where the structure of the deal determines who gets to participate in homeownership at all.
Want to connect with Michael? You can follow him on Instagram, Facebook, TikTok, or LinkedIn, visit his personal website for more details, or send him an email directly.