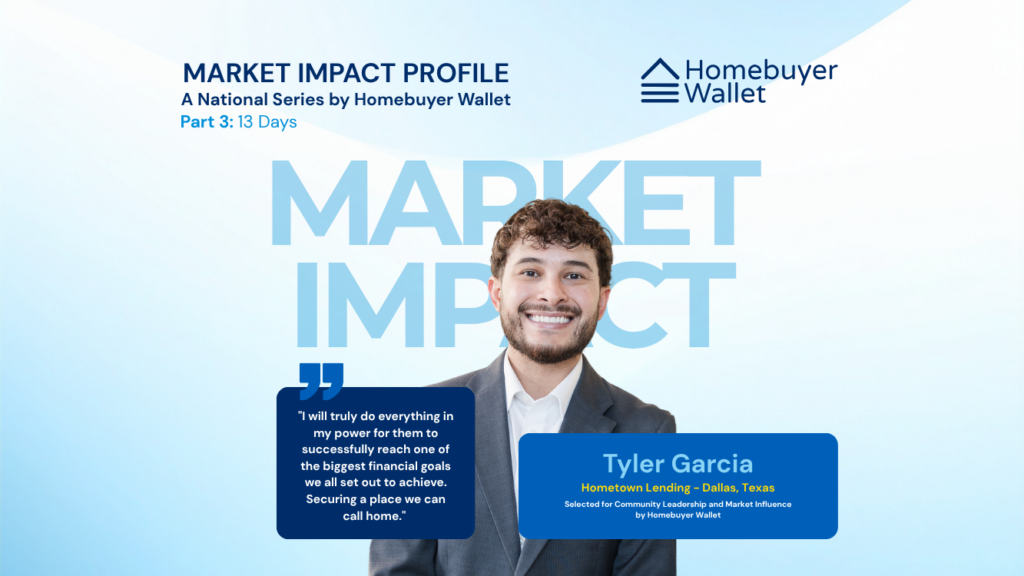
Tyler Garcia helped newly married first-time buyers win a $450,000 single-family home near Lake Highlands and White Rock Lake in Dallas, Texas, by making their financed offer faster than cash. The competing cash offer needed more time, so Garcia and the Realtor committed to a closing timeline of 14 days or less and finished the loan in 13.
Financing Speed Became the Buyer’s Leverage
In a competitive offer situation, buyers often assume cash will beat financing. In this Dallas transaction, Garcia proved the stronger offer was the one the seller could rely on sooner. The buyers did not win because they removed every financing step from the deal. They won because Garcia made the financing timeline tight enough to change how the seller viewed risk.
“My Realtor and I helped a first-time buyer’s offer get accepted over a cash offer because we offered a fast closing, 14 days or less. We did it in 13,” Garcia said. “The cash offer took some more time. In this case our clock won.”
That clock mattered because the buyers were not investors or repeat purchasers with unlimited flexibility. They were newly married first-time buyers who wanted to start a family and put down roots in Dallas. The home near Lake Highlands and White Rock Lake was not just a transaction target. It was the place where their next stage of life could begin.
Financing speed means turning loan execution into offer strength. In this case, Garcia used the lender’s timeline, processing control, and appraisal urgency to make a financed buyer more competitive than a slower cash buyer.
The First Few Days Controlled the Contract
A 13-day closing leaves little room for passive loan handling. Garcia had to compress the most time-sensitive parts of the mortgage process into the first stretch of the contract, because one delayed document, appraisal slot or processing review could have erased the advantage that won the offer.
The hardest part was closing a full loan from start to finish with a full appraisal inside a 14-day window. Garcia did not treat the appraisal as a routine milestone that could land whenever the system produced it. He identified it as one of the longest pieces of the file and moved it immediately.
“I operated with efficiency; my processing team and I put priority on this loan for the first few days to ensure the longest pieces were completed quickly,” Garcia said. “Mainly the appraisal and paying a rush for my client.”
That decision shows the practical difference between a fast promise and a fast closing. A lender can tell a listing agent that a buyer can move quickly, but the file still has to survive underwriting, appraisal, documentation and closing coordination. Garcia’s strategy worked because he front-loaded the bottlenecks instead of waiting for the transaction to become urgent later.
The True Cost Included More Than the Down Payment
The buyers did not use a formal homebuyer assistance program in this transaction. Instead, family gift funds helped cover a meaningful portion of the costs, which gave Garcia a clearer path to move quickly and document the file within the compressed timeline.
“No program used; they had family give gift funds to help on a good chunk of costs,” Garcia said.
On a $450,000 home, the buyer’s cash need depends on the loan type, down payment, closing costs, prepaid taxes, insurance, appraisal charges and any other transaction-specific costs. In this deal, the rush appraisal became part of the strategic cost of winning, because speed helped protect the contract. The buyers were not only budgeting for ownership. They were funding the execution required to make their offer credible.
That distinction matters for Dallas-area first-time buyers. A buyer may focus on the down payment first, but the offer strategy can create other immediate cash demands. A rushed appraisal, tight closing schedule, and fully documented gift funds all require coordination before the buyer reaches the closing table.
Daily Coordination Protected the Deal
Garcia’s role did not stop at loan qualifications. The 13-day timeline required him to keep every party moving in the same direction each day, because the contract depended on rhythm as much as approval.
“Constant communication was key; we had to make sure each day all parties were doing what they needed to do,” Garcia said. “We needed consistent cohesion and we had it.”
That cohesion included the buyer, Realtor, processing team, and appraisal process. Each party had to know what mattered next, what could not wait, and what had already been completed. In a normal timeline, a missed day can sometimes be absorbed. In this transaction, a missed day could have turned the seller’s confidence back toward the cash offer.
Garcia’s communication style gave the buyers a practical advantage. He did not rely on a single preapproval letter to carry out the offer. He kept the transaction alive after acceptance by making sure the financing behaved the way the offer promised it would.
Gift Funds Replaced Program Assistance in This Deal
Because no formal assistance program was used, Garcia’s strategy stayed centered on execution rather than program navigation. The family gift funds helped reduce the buyers’ direct burden, but they also had to be handled correctly inside the loan process. Gift funds can help with down payment and closing costs, but they still require documentation and timing discipline.
This is where buyer preparation changes the offer. A buyer who expects family help must know how much support is available, when funds can be documented and how the lender needs to verify them. Garcia’s ability to move fast depended on having that financial picture organized while the appraisal and processing work moved at the same time.
For buyers who do not have access to family gift funds, the cost-reduction search may need to start earlier. Down payment assistance, closing cost grants, builder incentives, employer housing benefits and other local options can change a buyer’s cash position before the offer stage. Homebuyer Wallet can help buyers identify those opportunities, but the key lesson from Garcia’s deal remains the same: the money must be matched to the timeline before the buyer competes.
The Strongest Offer Was the One the Team Could Execute
This Dallas transaction stood out because the result challenged a common assumption. Cash did not win automatically. A financed buyer won because Garcia and the Realtor made a promise the team could actually deliver.
The buyers needed more than access to a mortgage. They needed a lender who understood how speed, appraisal timing, documentation, and communication would affect the seller’s decision. Garcia’s value showed up in the pressure points that could have broken the deal: the short contract window, the full appraisal, the rush fee, the processing priority, and the daily coordination.
The transaction also reinforced why Garcia treats financing as part of the buyer’s life plan, not just a file to close. These buyers wanted roots in Dallas and wanted to start a family as soon as possible. The 13-day closing helped turn that personal goal into ownership.
“I will truly do everything in my power for them to successfully reach one of the biggest financial goals we all set out to achieve,” Garcia said. “Securing a place we can call home.”
Want to connect with Tyler? You can follow him on Instagram, Facebook, or LinkedIn, send him an email directly for more details.