Mika Walker helped first-time buyers in their 60s pursue a new construction home in Kellyville, Oklahoma, with less than $3,000 targeted out of pocket, a payment cheaper than rent and a deadline tied to keeping three siblings together in foster care. The buyers needed credit guidance, down payment assistance, closing cost support and a larger home within roughly 40 days, and Mika’s strategy turned a fragile timeline into a viable purchase path.
For Mika, a broker and Realtor with RedHearth Realty and Management serving the Tulsa Metro area, that outcome reflects the way she approaches affordability. She does not start by asking buyers what list price they like. She starts by identifying the payment they can safely carry, the cash they actually have, the programs they may qualify for and the concessions the current market may support.
Payment Strategy Changes the Search Before It Starts
Mika’s core advice to buyers in Tulsa, Oklahoma, is blunt because she believes it changes everything about the search. “You are approved for a payment — not a price,” she said. That sentence guides how she evaluates homes, lenders, financing options and long-term risk for clients who assume a lower price always means a better deal.
The distinction matters in the Tulsa Metro area because Mika often works with first-time buyers who look at homes in the $250,000 to $360,000 range. A typical purchase may be a 4-bedroom, 2-bath, 2-car single-family home with about 1,800 square feet, but the right structure can matter as much as the right floor plan.
Mika said some buyers begin with older homes around $250,000 because that price feels safer. When repairs, maintenance, insurance, lender terms and available incentives enter the conversation, she may show them a new construction home closer to $330,000 that can carry a similar payment. The new home may also include warranties, fewer immediate repair concerns and more usable long-term asset value.
That is where Mika’s background shapes the work. She entered real estate through investing, flipping, wholesaling and rentals before moving from engineering into real estate full time. That history gives her a mathematical and repair-focused lens, and she uses it to show buyers how payment, condition and future costs interact.
“I focus mostly on the financial picture, as that is how I see real estate — a home is an asset, and I help my client manage it,” Mika said. She still understands that a house has to feel like home, but she does not let emotion hide the numbers that determine whether the purchase will help or hurt a buyer later.
Financing access in Mika’s Tulsa Metro practice means using payment-based approval, assistance programs, lender selection and negotiated concessions to turn limited cash on hand into a practical path to ownership.
Assistance Programs Turn Limited Savings Into Buying Power
Mika gets involved in the financial and credit picture before clients fall in love with a property. She wants to know how much cash they have, what their credit profile looks like, what payment they can handle and whether their lender has matched them with the right product. That early work allows her to decide whether down payment assistance, low-down-payment financing or new construction incentives should guide the search.
In the Tulsa Metro area, Mika said typical down payments for her buyers may range from $0 to $10,000. Estimated closing costs often fall between $5,000 and $8,000, while typical monthly payments land around $1,700 to $2,300. Those numbers make the structure of the deal especially important because a buyer may qualify on income but still lack the cash to close without the right assistance or negotiation.
Mika frequently uses the Oklahoma Housing Finance Agency’s OHFA Homebuyer Down Payment Assistance program with FHA financing when it fits the buyer. The benefit is direct: It can help qualified Oklahoma buyers reduce the amount they need to bring to closing while using FHA financing’s lower down payment structure. Mika does not treat the program as a slogan. She uses it as one piece of a larger plan involving payment, credit, cash to close and property selection.
She also mentioned REI Oklahoma assistance with conventional financing as another path for buyers who may be better served outside FHA financing. For some borrowers and properties, conventional financing paired with assistance can create a cleaner route than forcing every buyer into the same loan type. Mika’s role is to help clients understand which structure gives them the strongest chance to close while preserving their financial position after closing day.
USDA financing also matters in Mika’s market because eligible buyers and eligible properties can benefit from low- or no-down-payment options. Around the Tulsa Metro area, that tool can be relevant when a buyer’s location, income and property choice align. Mika uses it when it helps a buyer solve the cash problem without creating a payment problem.
The point is not that every buyer should chase every program. Mika’s strategy depends on matching the buyer’s actual financial picture to the loan product, assistance source and property type that can survive underwriting, appraisal and inspection. That is why she says buyers make a mistake when they do not shop lenders.
Concessions Create Room Where Buyers Feel Stuck
Mika sees another opening for Tulsa Metro buyers right now: concessions. She said inventory has risen from recent years, qualified buyers have become harder to find and negotiations have shifted in buyers’ favor. In that environment, she does not let clients assume the listed price and standard closing costs are fixed.
“Ask for concessions from sellers — you’ll get them,” Mika said. The line reflects her direct style, but it also reflects a practical reading of the current market in Tulsa, Oklahoma, and nearby communities. If sellers or builders need qualified buyers, Mika uses that leverage to reduce the buyer’s upfront burden.
Concessions can matter more than a small price reduction for buyers with limited cash. A lower purchase price may slightly reduce the payment, but a seller credit can help cover closing costs that would otherwise block the transaction. For a buyer with income but little cash, that difference can decide whether the home closes at all.
Mika applies the same logic to new construction incentives. A builder credit, rate incentive or closing cost contribution can change the monthly payment and cash-to-close calculation enough to make a newer home competitive with an older resale home. That is why she does not separate negotiation from financing. In her model, the offer terms and loan structure have to work together.
Her approach also protects buyers from overspending on the wrong first home. Mika said many buyers try to purchase their “forever home” before they are ready and end up spending more money while still feeling dissatisfied. She redirects them toward the home that fits the current financial stage, builds stability and leaves room for future options.
Lender Selection Determines the Real Budget
Mika’s financing strategy depends heavily on lender selection because the wrong preapproval can distort the entire search. She said one of the most common buyer mistakes in the Tulsa Metro area is failing to shop lenders. A buyer may think they know their budget, but lender knowledge, loan product access and program familiarity can change both the payment and the cash required to close.
“I am intricately involved in the financial/credit picture from the get-go,” Mika said. That involvement allows her to catch issues before they become contract problems. She can spot when a buyer needs a different lender conversation, a different loan structure or a different property strategy.
Tulsa Metro buyers also face local details that can change their approval amount. Mika said school districts carry major pricing and value implications, and county tax differences can affect what a buyer qualifies for. A buyer looking in Tulsa County may not have the same preapproval room as a buyer looking in Wagoner County, even if the purchase price looks similar.
Insurance has also become a sharper part of the analysis. Mika said premiums have been tougher in recent months, and insurers have become more selective. That makes payment-based planning even more important because insurance can alter the monthly cost and narrow a buyer’s room to qualify.
Mika does not present these issues as abstract warnings. She uses them to refine the buyer’s search before the contract. The home has to work for the lender, the insurer, the buyer’s payment, the buyer’s cash and the buyer’s future maintenance risk.
A Kellyville Purchase Proved the Strategy Under Pressure
The Kellyville, Oklahoma, transaction showed how Mika’s financing access strategy works when the stakes are high. The buyers were first-time purchasers in their 60s who needed a stable home quickly so they could gain possession of three siblings in foster care. They needed a larger home, help with credit, down payment assistance and a structure that would not require cash they did not have.
The buyers found Mika on Facebook after seeing her content repeatedly. The wife told Mika she had picked up her phone three different times and Mika appeared, leading her to say, “This girl is either a scam or sent by God.” When she called, Mika walked through their finances, timeline and preferred area, then identified what could work.
“They had almost nothing in the bank, but he made really good money,” Mika said. That difference became the heart of the strategy. The buyers did not lack income potential; they lacked time, cash to close and a clear financing path.
Mika focused on a new construction neighborhood in Kellyville, Oklahoma, where the buyers could pursue a 4-bedroom, 2-bath, 2-car single-family home in the $230,000 to $240,000 range. She had to secure paid closing costs and help get a mobile home school building approved by the homeowners association, a challenge she described as harder than it might sound.
The home also carried emotional weight. The buyers had lost a similar floor plan years earlier after a lease-to-own arrangement failed because of improper documentation. When they walked into the right house in Kellyville, the wife nearly fell to her knees crying, and her husband recognized it immediately as home.
The timeline grew more complicated when weather extended the build process. Mika responded by getting the actual builder involved in providing documentation for the judge and court so the buyers would not lose the chance to bring the children home. The transaction required persistence across lending, construction, HOA approval and court timing.
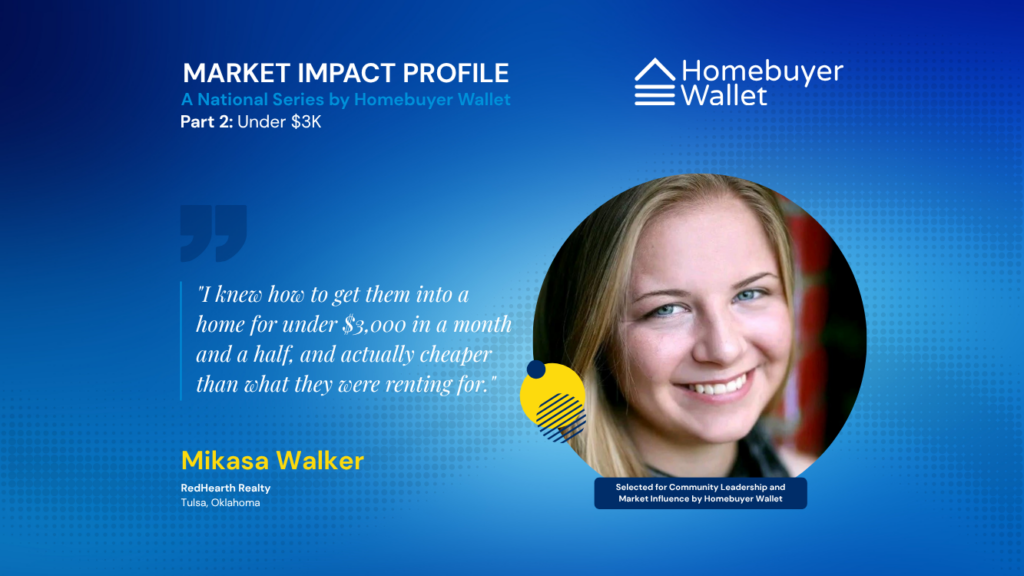
“I knew how to get them into a home for under $3,000 in a month and a half, and actually cheaper than what they were renting for,” Mika said. That sentence captures the market impact of her work more clearly than any general affordability claim could. She used the financing tools, concessions and coordination required to make the numbers serve the family’s urgent goal.
Ownership Becomes Possible When the Math Gets Clear
Mika’s work matters in the Tulsa Metro area because many renters may be closer to ownership than they realize. She said median rents are about $100 per month less than what a buyer can pay for a new 3-bedroom home with $0 down. That comparison does not mean every renter should buy immediately, but it shows why Mika pushes buyers to test the math before assuming ownership is out of reach.
Her social media marketing focuses heavily on affordability because she wants current renters to understand what may be possible. She uses education to get attention, but her value appears in the details that follow: lender fit, credit review, assistance options, concessions, property condition and long-term cost. Those details turn curiosity into a workable plan.
Mika’s edge comes from combining technical competence with a fiduciary mindset. She said great agents in her market separate themselves through conscientiousness, not sales ability alone. That standard shows up in how she runs numbers, evaluates repairs, checks financing and positions buyers for negotiations.
The Tulsa Metro market still requires discipline. Buyers have to understand taxes, insurance, school district value, lender differences and the trade-offs between resale and new construction. Mika’s role is to make those moving parts legible before a buyer commits.
For low-cash buyers, the result can feel surprising. A buyer who thought savings were the only barrier may discover that payment, assistance, concessions and property choice can shift the outcome. Mika’s strategy does not promise that every renter can buy, but it proves that some buyers who feel stuck have not yet seen the right version of the numbers.
That is the impact Mika brings to Tulsa, Oklahoma, and the surrounding metro area. She does not simply help buyers find homes they like. She helps them find the structure that lets the home become possible.
Want to connect with Mikasa? You can visit her website, follow her on Instagram, Facebook, or TikTok, or send her an email directly for more details.