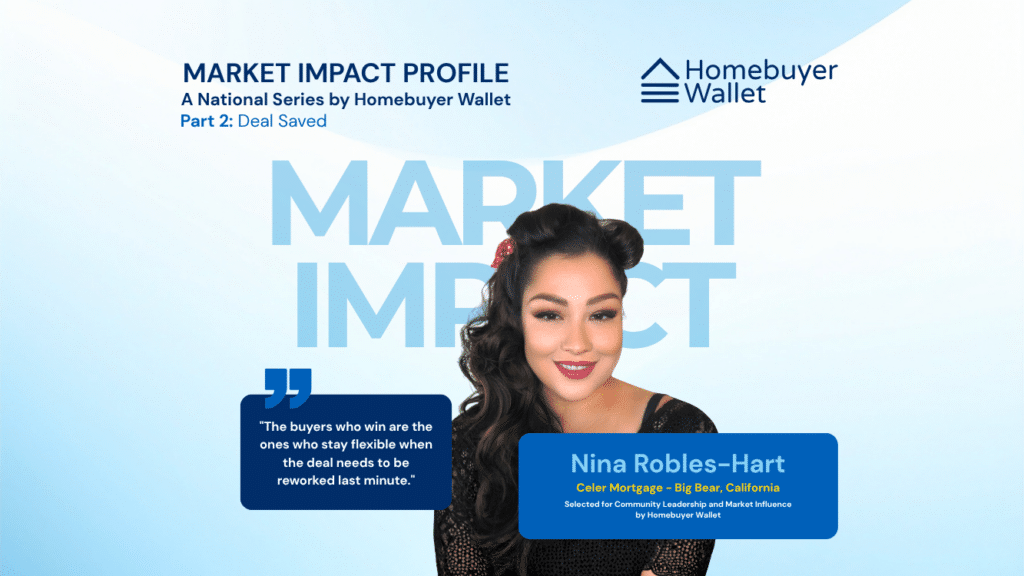
In California, Nina Robles-Hart often works with buyers in the $400,000 to $750,000 range, where a file can look workable on paper and still fall apart once the cash-to-close numbers tighten. A buyer may budget 3.5% down, or about $14,000, then run into another $12,000 to $14,000 in closing costs on a 30-day timeline, with expected monthly payments landing between $3,200 and $4,500. Robles-Hart’s market impact shows up in that gap. She restructures the deal fast enough to keep the buyer in contract when the original financing plan no longer works.
Deal restructuring is rebuilding the financing plan before the contract dies. In Robles-Hart’s version of that work, the shift usually comes after a buyer has already found the house, committed emotionally and realized the seller cannot cover enough of the closing costs to make the numbers hold. Instead of treating that moment as the end of the transaction, she treats it as the point where strategy begins.
The Deal Often Breaks at the Cash-to-Close Stage
Robles-Hart’s buyers are not chasing fantasy numbers. They are trying to buy real California homes, often around 1,500 square feet, in the form of single-family residences and condos, and they are doing it in a price band where even a “low down payment” still leaves a meaningful cash burden. The issue is not simply that homes are expensive. The issue is that the structure of the deal can change after the buyer already believes the financing is set.
That is where Robles-Hart sees buyers get trapped by a false sense of security. They may have enough cash in the bank to show a down payment and feel like the hardest part is behind them, but the contract still has to survive closing costs, reserve requirements and the seller’s willingness to contribute. In her market, that shift happens often enough that the original plan cannot be treated as permanent.
Approval Does Not Cover the Reserve Gap
Robles-Hart is blunt about one mistake she sees repeatedly in California purchases. “Not having a 401k or savings for reserves, just because you qualify for the loan, most banks still want to see you have 2 months of mortgage payments just sitting in your bank.” That quote captures the difference between getting approved and being positioned to close.
Her value is not that she tells buyers to save more in the abstract. Her value is that she builds around the reserve issue before it wrecks the transaction. In a market where the payment can land between $3,200 and $4,500 a month, two months of reserves is not a small technicality. It is a real liquidity test, and if the buyer drains too much cash at the front end, the file becomes harder to hold together when underwriting tightens.
That reserve pressure changes the meaning of every concession in the deal. A missing seller credit does not just increase closing costs. It can also wipe out the cash cushion the lender wants to see after closing. Robles-Hart’s financing decisions are shaped by that reality, which is why she does not treat down payment money, closing-cost money and reserve money as separate conversations.
CalHFA Creates Room to Rebuild the File
When Robles-Hart talks about programs she has used with clients, she points directly to CalHFA, the California Housing Finance Agency, as a source of assistance in transactions that need to be reworked. CalHFA offers first-mortgage and down payment assistance options for California homebuyers, which is why it fits the kind of restructuring work Robles-Hart describes.
What matters in her process is not the label on the program. It is the timing and the purpose. A buyer may enter escrow assuming the seller will help with closing costs, only to find out later that the seller will not cover enough to make the transaction comfortable. At that point, Robles-Hart does not cling to the original structure. She rebuilds it so the buyer can preserve more of their own liquidity and still move forward.
She describes that turning point clearly: “Most of the time, I see down payments in bank accounts thinking we have a deal, then the buyer ends up loving the home of their dreams and the seller cannot cover closing costs so I end up restructuring the deal to a down payment assistance program and the buyer ends up covering their own closing costs.” The important detail in that sentence is not just that she uses assistance. It is that she uses assistance after the deal changes, not only before the search begins.
That distinction gives the article its core logic. In Robles-Hart’s hands, down payment assistance is not only an entry tool for buyers who start with low cash. It is also a rescue tool for buyers whose original numbers no longer hold once the contract gets real. That is why her work produces a result many buyers do not know is possible: the same buyer, the same home, a different structure, and a deal that still closes.
A Softer Market Still Requires a Hard-Nosed Strategy
Robles-Hart sees California moving toward a buyer’s market, and that shift matters because it creates more room to negotiate for closing-cost credits or a rate buydown. She is not describing a market where buyers can coast. She is describing a market where leverage exists, but only if the financing structure is strong enough to use it.
That is an important distinction in her approach. More negotiating room does not erase the need for backup plans. It simply changes the menu of outcomes available inside the same 30-day closing window. A buyer may get a seller credit, a rate buydown or both, but Robles-Hart does not build the entire file on the hope that the seller will solve the problem. She keeps a second structure ready because California deals do not reward emotional assumptions.
Her own language on that point is direct. “You have to not think emotionally anymore.” In context, that is not cold advice. It is transaction discipline. Once a buyer falls in love with a property, especially in a market where they feel they have finally found the right house, emotional thinking can make them cling to the first version of the deal even after the math has changed.
That is also why she sees opportunity in fixer-uppers that barely pass inspections and appraisals. Those properties can create openings inside a competitive market, but only for buyers whose financing can absorb uncertainty without collapsing. Robles-Hart’s role is to keep the structure flexible enough that an imperfect property or an imperfect negotiation does not automatically end the purchase.
Hidden California Costs Change the File Before Closing
Robles-Hart’s market knowledge becomes most valuable when the threat to the deal is not obvious from the listing price alone. In California, she says, solar panels on new builds are mandatory, and solar agreements now show up on many other homes as well. If the buyer already has a high debt ratio, that extra obligation can damage the file unless the agreement is reviewed early enough to adjust the strategy before escrow is in danger.
She is equally alert to the recurring costs buyers underestimate when they reach for a “nicer” neighborhood. HOA dues and Mello-Roos can change the affordability picture fast, even for buyers who thought they had already stretched successfully into the target area. In Robles-Hart’s market, the purchase price is only the beginning of the underwriting story. The real pressure often arrives through monthly obligations that make a file look weaker after the search is already emotionally advanced.
That is why her restructuring work is not a generic down payment conversation. It is a California-specific response to a California-specific squeeze. She is watching the reserve requirement, the seller-credit reality, the solar obligations, the HOA or Mello-Roos burden and the speed of escrow at the same time. Her strategy works because she treats all of those numbers as part of one system.
The Win Is Preserving the Path to the Home
The strongest line in Robles-Hart’s transcript is also the cleanest description of how she sees her job. “As long as the buyer is happy, then I am happy to find or restructure last minute.” That is not the language of a professional trying to defend the original deal at all costs. It is the language of someone who understands that the win is not preserving the first draft of the financing. The win is preserving the buyer’s path to the home.
In practical terms, that means the buyer may not close exactly the way they expected when they first wrote the offer. They may end up covering their own closing costs after all, or shifting the way the down payment is sourced, or leaning on assistance that was not part of the initial plan. What Robles-Hart changes is the outcome of that surprise. Instead of letting the file die at the point where cash, reserves and seller behavior stop lining up, she rebuilds the transaction around what the buyer still needs to succeed.
That is the real market impact in her California practice. She is not just helping buyers find money. She is helping them survive the moment when the structure they expected gives way and a second structure must appear fast enough to keep the contract alive. In a market where buyers are already carrying high prices, meaningful closing costs and narrow liquidity margins, that ability can make the difference between losing the house and getting the keys.
Want to connect with Nina? You can follow her on Instagram, Facebook, TikTok, or LinkedIn, or send her an email directly.