Justine Hilgenberg’s Anaheim Hills, California, transaction shows why buying in a desirable neighborhood requires more than qualifying for the payment and liking the house. In a single-family home purchase near Mabury, a move-up couple found the schools, low-crime setting and family-oriented location they wanted, but the deal also revealed two risks buyers often miss: neighborhood conditions that change by time of day and title issues that can threaten a closing even when the purchase feels smooth.
Market Fit Starts Before the First Offer
The buyers were a married move-up couple with two small to medium-sized dogs. They wanted a home where they could start a family, stay close to amenities, access strong schools and feel comfortable letting children play outside. Hilgenberg did not treat those goals as vague lifestyle preferences. She used them to narrow the search to specific pockets of Anaheim Hills where the neighborhood conditions matched the way the buyers wanted to live.
“I took their criteria and I narrowed it down to certain neighborhoods that were within walking distances to schools and where it’s safe to let kids go out and play without having to worry about their safety,” Hilgenberg said. That sentence explains the practical work behind a local search. The value was not just finding a house in Anaheim Hills; it was filtering the market through school access, safety, daily routines and long-term family use.
Buying in Anaheim Hills requires more than qualifying for the payment; buyers need an agent who can explain neighborhood conditions, structure a practical offer and keep title or escrow problems from turning into closing delays.
Anaheim Hills Due Diligence Extends Beyond the Showing
The property sat near Mabury in Anaheim Hills, across from a large mountainous area. That location gave the home access to the natural setting many buyers like in hillside communities, but it also created a condition that would not show up in listing photos. Wildlife moved through the area at night, including coyotes and other predatory animals coming down from the hills.
Hilgenberg said she warned the buyers before closing. “I specifically brought this to the buyers attention as they purchased right across the street from a huge mountainous area where there are several predatory animals that come to roam the neighborhoods at night looking for food.” The buyers did not visit the property during the day, at night or on weekends, to understand the neighborhood rhythm before they closed.
That decision became more than a minor oversight. After closing, Hilgenberg received a call about the number of coyotes moving through the area, and one of the buyers’ smaller dogs had been attacked. The transaction stood out to her because the risk was visible to someone who knew the area, but it required the buyers to take the local warning seriously before the purchase became permanent.
For Anaheim Hills buyers, that lesson belongs inside the buying process. A showing reveals the house, but repeated visits reveal the neighborhood. Traffic patterns, barking dogs, wildlife, lighting, parking, weekend activity and hillside conditions can all affect whether a home works for the buyer’s actual life.
A Reasonable Asking Price Still Needed a Clean Strategy
The offer strategy did not depend on drama or overbidding. Hilgenberg recommended that the buyers offer the asking price because she believed it was reasonable for the property and market position. That advice kept the buyers competitive without pushing them into unnecessary escalation.
“I recommended that they offer what was being asked as it was reasonable,” Hilgenberg said. She also made sure the buyers submitted their pre-qualification up front, which helped signal that they were prepared to perform. In a desirable neighborhood, that kind of documentation can matter because it gives the seller more confidence in the buyer’s ability to close.
Hilgenberg also separated repair requests from credit requests. That distinction matters during inspection negotiations because buyers and sellers often respond differently to physical fixes than they do to dollar credits. A repair request asks the seller to coordinate work before closing, while a credit can give the buyer more control after closing if the lender, contract and escrow structure allow it.
Commission was also part of the negotiation. Hilgenberg treated the offer as a full package rather than a single price number, which gave the buyers room to address cost, certainty and seller expectations together. That practical structure fit the transaction because the buyers wanted the home, the price was reasonable and the path to closing depended on clean execution.
Contract Timelines Reward Patience and Compromise
Hilgenberg’s negotiation advice focused on patience, flexibility and risk management. She told the buyers that transactions can run longer than expected and that they needed to think carefully about how each request would land on the seller’s side. That guidance became important because even a mostly smooth transaction can develop friction once inspections, escrow and title review begin.
“Be patient as these things can run longer than expected, put yourself in the sellers shoes when asking for items, costs, timing… and then to be flexible and compromise on hiccups that came up that weren’t necessarily the fault of anyone such as a title issue or escrow issue,” Hilgenberg said. Her advice did not ask the buyers to give up leverage. It asked them to use leverage with judgment.
That approach matters in a real purchase because every demand has timing attached to it. Repairs can create delays. Credits can require lender approval. Escrow issues can add document work. Title issues can force parties to solve old problems before a new buyer can take ownership cleanly.
For buyers, the contract period is not just a waiting room between accepted offer and closing. It is the stage where the buyer, seller, agents, escrow, title and lender must keep the file moving at the same time. Hilgenberg’s role was to help the buyers stay focused on the outcome without ignoring the issues that still had to be solved.
Title Issues Became the Hidden Closing Risk
The most complicated part of the transaction involved title. Hilgenberg said child support, old liens and a misunderstanding on certain documents had to be cleared before the deal could close. Those issues did not come from the buyers’ financing or their interest in the home, but they still affected the buyer’s timeline.
Hilgenberg’s response was hands-on. She physically picked up documents for the seller and took them to escrow. She also helped get the title company to hold funds on the support judgment instead of allowing that issue to delay the transaction.
“When I went and physically picked up the documents for the seller to take to escrow and was able to get the title company to hold funds on the support judgment instead of delaying the transaction,” Hilgenberg said, describing the moment she felt she had clearly helped her clients. That action shows the difference between monitoring a transaction and actively moving it forward.
The lesson for buyers is direct: title problems can become financial and timing problems if no one understands what needs to happen next. A lien, judgment or document error can interrupt closing even when the buyer has loan approval and the seller wants to sell. Hilgenberg’s value came from knowing when communication was not enough and when the file needed physical coordination to keep the closing on track.
The True Cost Includes Cash, Carrying Costs and Local Risk
The financial side of buying in Anaheim Hills starts with the visible numbers. A buyer considering a $1 million single-family home might plan a down payment, closing costs, property taxes, homeowners insurance and the monthly mortgage payment. If the buyer put 10% down, the down payment would be $100,000 before closing costs. If closing costs ran 2% to 3% of the purchase price, that would add roughly $20,000 to $30,000 before credits, prepaid items or negotiated concessions.
The monthly cost also extends beyond principal and interest. Orange County property taxes, homeowners’ insurance and any applicable HOA dues can change the real payment. In hillside or higher-risk areas, insurance review can become more important because carriers may evaluate location, wildfire exposure, slope, property condition and coverage history before issuing a policy.
Those numbers explain the budget, but Hilgenberg’s transaction shows that the true cost also includes what buyers fail to check. A buyer who does not visit home at different times may miss the neighborhood conditions that shape daily life. A buyer who does not understand inspection of credits, repair negotiations or title timing may misread the closing process. A buyer who assumes a smooth transaction will stay smooth may not be prepared when old liens or support judgments affect the file.
Cost reduction strategies still matter. Buyers may reduce upfront cash through seller credits, lender credits, closing cost grants, down payment assistance or employer housing programs when they qualify. HomebuyerWallet can help buyers identify homebuyer programs that may reduce the cash needed to purchase, but the program search should sit alongside local due diligence, not replace it.
Hilgenberg’s approach ties those pieces together through communication. “I am very familiar with the area and I was very keen on keeping communication at the forefront and making sure they understood everything before moving forward,” she said. In this Anaheim Hills purchase, that meant narrowing the search around family goals, warning the buyers about wildlife risk, structuring a practical offer and solving title issues before they could slow the closing.
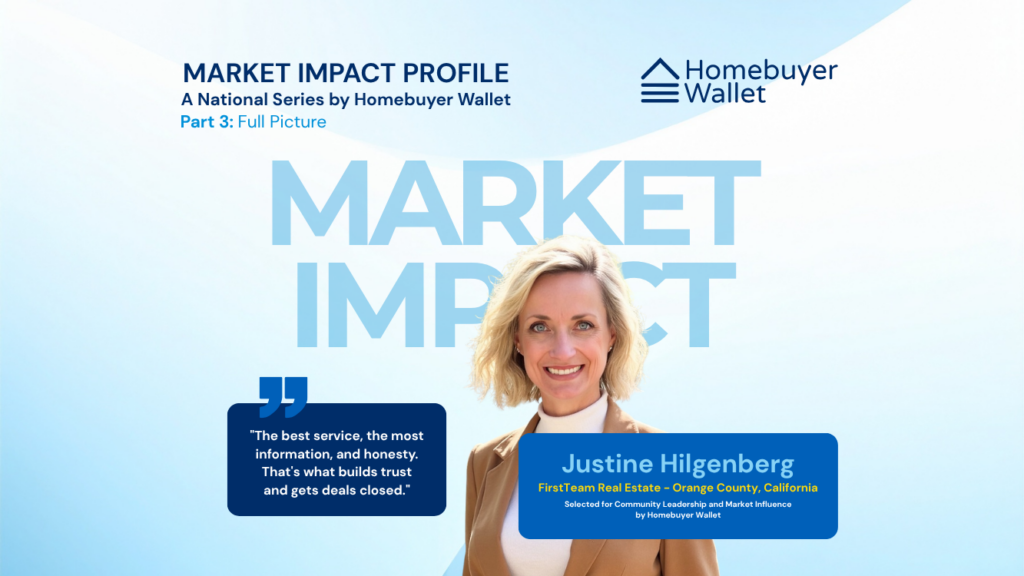
Her service model is direct: “The best service, the most information, and honesty which builds trust.” For buyers in Anaheim Hills, that combination matters because the purchase is not finished when the home looks right online. The process works when the buyer understands the neighborhood, the offer, the contract, the title file, and the real cost of living with the decision after closing.
Want to connect with Justine? You can follow her on Instagram, Facebook, or LinkedIn, send her an email l directly or visit her personal website for more details.